There is a moment many business owners reach where the math stops working. Not because revenue disappeared, but because the cost of carrying multiple funding products at once — a merchant cash advance with daily remittances, a short-term loan with weekly payments, a couple of stacked credit card balances, maybe an equipment note — quietly eats the margin that was supposed to fund growth. At ASAP Capital Solutions, Ashley and Damon Boswell see this pattern constantly, and the owners who reach that moment are not irresponsible. They made individual decisions that each made sense at the time. The problem is that those decisions, stacked together, created a debt load the business can no longer comfortably carry.
That is where business debt consolidation enters the conversation. Consolidation is not a magic eraser — it does not eliminate what you owe. What it can do is restructure multiple obligations into a single, more manageable payment, ideally at a lower overall cost and over a longer, more sustainable term. In this guide, Ashley and Damon Boswell break down what business debt consolidation actually is, when it makes sense, how it compares to simple refinancing, the risks every owner must manage, and how to approach restructuring without falling into a new trap.
What Is Business Debt Consolidation?
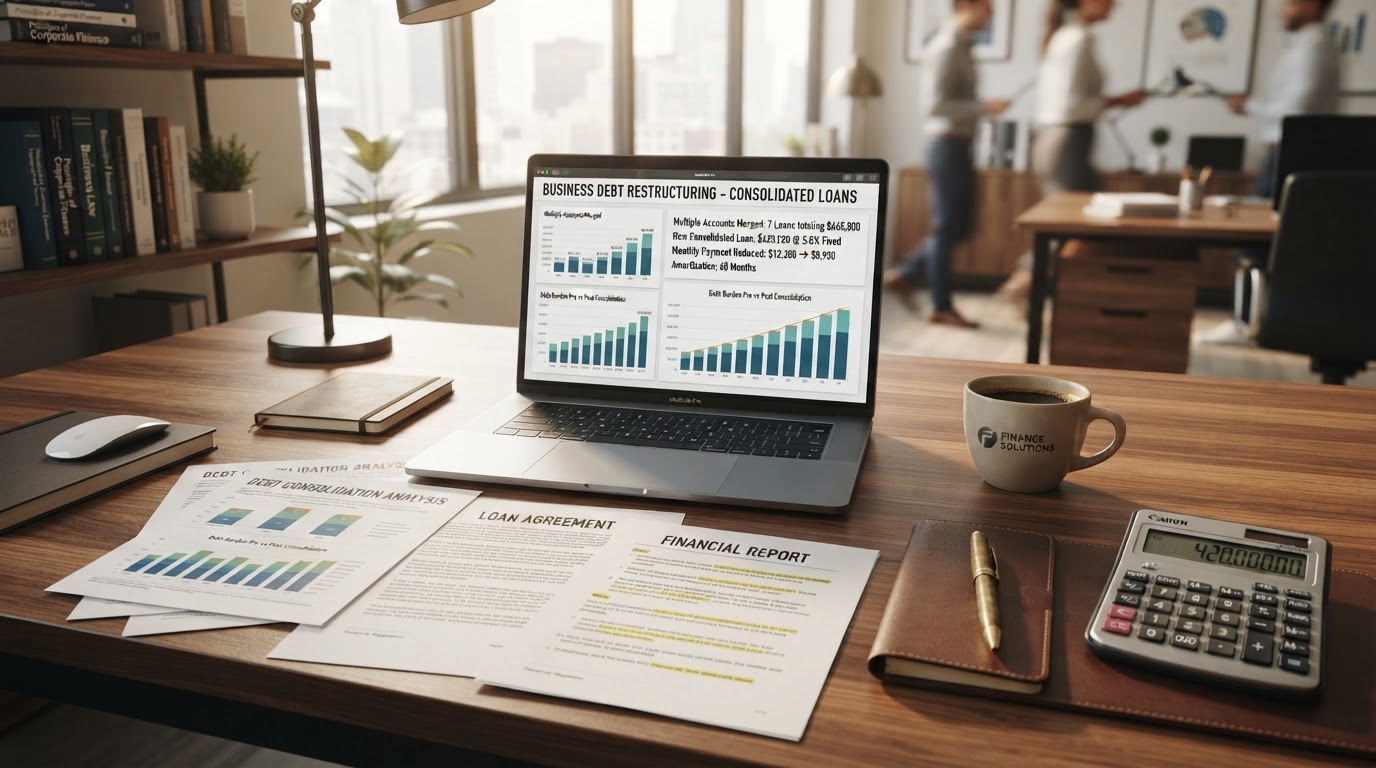
Business debt consolidation is the process of taking out a single new loan or financing facility and using the proceeds to pay off multiple existing debts, leaving the business with one monthly payment instead of several. As Nav explains, debt consolidation combines multiple debts into a single loan with one monthly payment, ideally at a lower interest rate and with a longer repayment term that reduces the monthly burden. The goal is not to borrow more — it is to borrow smarter, replacing a tangle of high-cost, short-term obligations with a single, structured, predictable payment.
Ashley Boswell describes it in practical terms for every owner she speaks with: consolidation takes five payments hitting on five different schedules and turns them into one payment on one schedule. That simplification alone can restore cash flow breathing room, but the real value comes when the new loan carries a lower rate or a longer term than the debts it replaces. Damon Boswell adds that consolidation is distinct from simply taking another advance to cover the last one — which is stacking, not restructuring. Stacking compounds the problem. Consolidation, done correctly, unwinds it.
Consolidation vs. Refinancing: Knowing the Difference
The terms consolidation and refinancing are often used interchangeably, but Ashley and Damon Boswell are careful to distinguish them because the strategy differs. Refinancing means replacing a single existing loan with a new one — typically to secure a lower interest rate, a longer term, or better terms. Consolidation means combining multiple debts into one new loan. As NerdWallet notes, refinancing replaces an existing loan with a new one, while consolidation specifically rolls multiple debts into a single payment. You can refinance without consolidating, and you can consolidate without refinancing in the strict sense, but the most powerful moves often do both at once — rolling several debts into one new loan at better terms.
Damon Boswell's guidance is to start by identifying the goal. If the problem is that one specific loan has an uncompetitive rate, refinancing that single loan may be enough. If the problem is that multiple obligations are competing for the same cash flow each month, consolidation is the right framework. Ashley Boswell adds that many owners do not realize they can do both simultaneously — pay off several high-cost debts with a single lower-cost loan, simplifying the payment schedule and reducing the total cost at the same time. That combination is where consolidation delivers its greatest value.
When Debt Consolidation Makes Sense
Consolidation is not always the right move, and Ashley and Damon Boswell are candid about when it is and is not appropriate. The strongest case for consolidation exists when a business is carrying multiple high-interest or short-term obligations — particularly merchant cash advances with daily or weekly remittances — and the combined cost is straining cash flow to the point that operations or growth are suffering. Forbes notes that debt consolidation is worth considering when you are struggling to manage multiple debt payments, when your current interest rates are high, or when you can qualify for a consolidation loan at a meaningfully lower rate than what you currently pay.
Damon Boswell identifies three signals that consolidation deserves a serious look. First, your total monthly debt service consumes a disproportionate share of revenue, leaving too little for operations and growth. Second, you are juggling three or more separate funding products with different payment schedules, creating administrative chaos and increasing the risk of a missed payment. Third, you have improved your credit or revenue profile since taking on the original debts, meaning you may now qualify for a lower-cost facility than was available to you at the time. Ashley Boswell adds a fourth: when the daily or weekly remittances of an MCA are actively preventing you from building the reserves you need to break the cycle. In that situation, converting a daily-payment obligation into a single monthly payment can be transformational for cash flow.
How Much Can You Save?
The savings from consolidation come from two sources: a lower interest rate and a longer repayment term. Bankrate explains that a debt consolidation loan can lower your monthly payment in two ways — by securing a lower interest rate than what you currently pay, and by extending the repayment term so each monthly payment is smaller. Both reduce the monthly burden, though they work differently. A lower rate reduces the total cost of the debt. A longer term reduces the monthly payment but may increase the total interest paid over the life of the loan if the rate is not also improved.
Ashley and Damon Boswell walk every owner through both calculations. The monthly payment reduction is what restores cash flow today. The total cost comparison is what determines whether the consolidation is genuinely cheaper over the long run. Damon Boswell's rule is to model both: if the new loan lowers the monthly payment meaningfully and either reduces or only modestly increases the total cost, the consolidation is sound. If it lowers the monthly payment but dramatically increases the total cost because the term is stretched far beyond what the original debts required, the owner is trading short-term relief for long-term expense — and that trade should be made deliberately, not accidentally.
Types of Business Debt Consolidation
Several funding structures can serve as a consolidation vehicle, and Ashley and Damon Boswell help owners match the right one to their situation. A term loan is the most common — a lump sum used to pay off existing debts, repaid in fixed monthly installments over a set term at a defined interest rate. For owners with strong credit and solid financials, a traditional term loan from a bank or credit union may offer the lowest rate. For owners whose credit or revenue profile does not meet bank standards, an alternative term loan from an online lender can still deliver meaningful savings over the high-cost debts it replaces.
Damon Boswell adds that a business line of credit can sometimes serve as a consolidation tool for smaller debt loads, particularly when the debts being consolidated are themselves small and short-term. A secured loan, backed by business assets or real estate, can unlock a lower rate and larger amount — making it powerful for consolidating significant debt when the business owns collateral. Ashley Boswell notes that 0% credit card stacking is occasionally used to consolidate higher-rate credit card balances onto interest-free cards during a promotional window, though she stresses this requires the same discipline as any stacking strategy: a concrete plan to pay down the balance before the promotional period expires. The right vehicle depends on the amount of debt, the business's credit and collateral, and the rate improvement available.
Qualifying for a Consolidation Loan
Qualification for a consolidation loan follows the same principles as any business loan, but with a specific emphasis on debt-service coverage. Lenders want to see that the business's revenue can comfortably cover the new consolidated payment — and that the consolidation genuinely improves the picture rather than simply adding more debt. Nav notes that lenders will review your credit score, revenue, time in business, and existing debt obligations when evaluating a consolidation loan. The stronger each of those factors, the better the rate and terms available.
Ashley Boswell's preparation guidance is specific: gather statements for every debt you intend to consolidate, including the outstanding balance, interest rate or factor rate, and remaining term for each. Calculate your current total monthly debt service across all obligations. Then compare that figure to the projected monthly payment on the consolidation loan. Damon Boswell adds that lenders will calculate a debt-service coverage ratio — the business's net operating income divided by total debt service — and typically look for a ratio of 1.25 or higher. If your current debts push that ratio below 1.0, meaning your debt service exceeds your available cash flow, consolidation is not just an option — it is likely a necessity. The key is showing the lender that the consolidation will bring that ratio back into healthy territory.
The Risks: What Every Owner Must Manage
Consolidation carries real risks, and Ashley and Damon Boswell are direct about every one of them. The most dangerous is the temptation to re-accumulate debt after consolidating. As Bankrate warns, if you consolidate your debts but then run up new balances on the credit cards or lines of credit you just paid off, you end up in a worse position than before — carrying both the new consolidation loan and the freshly accumulated debt. Damon Boswell sees this pattern destroy otherwise sound consolidation plans. The credit cards that were paid off must be closed, frozen, or used with strict discipline, or the cycle simply restarts.
Ashley Boswell adds a second caution: extending the term to lower the monthly payment can cost more in total interest over the life of the loan, even if each payment is smaller. That trade is acceptable when cash flow survival demands it, but it should be made with full awareness of the total cost, not hidden behind the relief of a smaller payment. Damon Boswell notes a third risk specific to consolidating merchant cash advances: some MCA contracts include confessions of judgment or personal guarantees that are not automatically released when the advance is paid off through a third-party consolidation loan. Owners must confirm that paying off an MCA through consolidation fully satisfies and releases the original obligation, or they may face collection attempts on a debt they believed was settled.
Consolidating Merchant Cash Advances Specifically
Merchant cash advances deserve special attention in any consolidation discussion, because they are the debt type most likely to create the cash-flow crisis that drives owners to consolidate. The daily or weekly remittances of an MCA can consume a large share of incoming revenue, and when multiple MCAs are stacked, the combined daily drain can make it nearly impossible to cover fixed costs. Forbes notes that consolidating high-interest business debt — particularly merchant cash advances — into a single term loan with a lower rate and monthly payments can provide significant relief, but it requires qualifying for a loan large enough to pay off the advances in full.
Damon Boswell's approach to MCA consolidation is methodical. First, obtain the exact payoff amount for each advance from the provider — not the remaining balance on the original contract, but the current payoff figure, which may differ based on how repayment has progressed. Second, confirm whether the MCA contract allows early payoff and whether any prepayment penalties or fees apply. Third, structure the consolidation loan to cover the total of all payoffs plus a modest contingency, and ensure the new monthly payment is comfortably below the total daily and weekly remittances it replaces. Ashley Boswell stresses that the owner must then close the door to re-stacking — no new advances, no new daily-payment obligations — or the consolidation simply resets the clock on the same problem.
Building a Debt Management Plan
Consolidation is most effective when it is part of a broader debt management plan, not a standalone transaction. Ashley and Damon Boswell recommend that every owner who consolidates also build a plan to prevent the debt from reaccumulating. That plan starts with a clear understanding of why the original debts were taken on — was each one tied to a specific, revenue-generating purpose, or were some used to cover operating shortfalls that consolidation alone will not fix? If the underlying cash-flow problem remains, consolidation buys time but does not solve the root cause.
Damon Boswell's framework is practical: after consolidating, redirect a portion of the cash flow freed by the lower monthly payment into a reserve account, so the business has its own buffer the next time a gap appears rather than reaching for external funding. Review the debt schedule quarterly to track progress and confirm the consolidation is performing as projected. And establish clear criteria for when taking on new debt is justified — a specific return the capital must generate, a specific repayment source — so future borrowing decisions are deliberate rather than reactive. Ashley Boswell adds that the owners who succeed long-term treat consolidation as a reset point, a moment to restructure not just the debt but the habits that created it.
Consolidation vs. Other Debt Relief Options
Consolidation is one option among several for managing overwhelming business debt, and Ashley and Damon Boswell help owners understand the full landscape. Debt settlement — negotiating with creditors to accept less than the full amount owed — can reduce the total debt but severely damages credit and may trigger tax liabilities on forgiven debt. Bankruptcy, whether Chapter 7 liquidation or Chapter 11 reorganization, is a legal process of last resort that can discharge or restructure debts but carries long-lasting consequences for the business and its owners. As NerdWallet outlines, debt settlement and bankruptcy are far more drastic than consolidation and should generally be considered only when consolidation is not feasible.
Ashley Boswell's guidance is to view consolidation as the middle ground — less drastic than settlement or bankruptcy, but more structured than simply continuing to struggle. If the business's revenue can support a consolidated payment and the owner qualifies for a loan that improves the terms, consolidation is almost always preferable to settlement or bankruptcy. Damon Boswell adds that early action matters enormously: owners who explore consolidation while they are still current on their payments and their credit is intact have far more options than owners who wait until they have already defaulted. The worst time to seek consolidation is after the damage is done.
Is Business Debt Consolidation Right for You?
Damon Boswell's readiness test for consolidation is direct: Are you carrying three or more separate business debts with different payment schedules? Is your total monthly debt service consuming a disproportionate share of revenue? Do you have high-cost obligations — particularly MCAs with daily or weekly remittances — that are straining cash flow? Can you qualify for a consolidation loan at a rate and term that meaningfully improves your monthly payment and ideally your total cost? And are you committed to not reaccumulating the debt you consolidate? If you can answer yes to these, consolidation is a legitimate, strategic move. If your debt load is small and manageable, or if you cannot qualify for better terms than what you currently carry, consolidation may not deliver enough value to justify the effort.
If you are unsure where your business stands, that is exactly what our AI Funding Match Calculator is built to clarify. The calculator weighs your revenue, credit, timeline, and goals, and Ashley and Damon Boswell review every result personally. On a short phone call — no Zoom required — we will help you assess whether consolidation is the right path, what structure fits your debt load, and whether your business qualifies for the terms that would make it worthwhile.
The Bottom Line
Business debt consolidation is not a cure-all, but for owners drowning in multiple high-cost, short-term obligations, it can be the difference between a business that survives and one that collapses under its own debt schedule. The owners who use it successfully consolidate deliberately — matching the right vehicle to their debt load, confirming that the new terms genuinely improve both the monthly payment and the total cost, and closing the door to reaccumulation so the cycle does not restart. Ashley and Damon Boswell have helped owners across the United States, Puerto Rico, and Canada restructure their debt and reclaim their cash flow, and the businesses that succeed are the ones that treat consolidation as a reset point for their entire financial strategy, not just a one-time transaction.
See whether debt consolidation fits your business. Complete the AI Funding Match Calculator in under 60 seconds, and Ashley and Damon Boswell will walk through your debt schedule, your consolidation options, and your next step on a quick phone call — so your capital starts working for your business again instead of against it.
Ashley Boswell and Damon Boswell
Funding specialists at ASAP Capital Solutions, helping business owners find the right capital across the United States, Puerto Rico, and Canada.
Find Your Funding Match in 60 Seconds
Complete the AI Funding Match Calculator and Ashley and Damon Boswell will review your matches on a quick phone call.
Get My Funding Match