Few funding products generate as much confusion — and as much caution — as the merchant cash advance. Business owners hear the words and immediately think of predatory rates and daily payments that drain the bank account. At ASAP Capital Solutions, Ashley and Damon Boswell work with MCAs every day, and their message is more nuanced than the headlines suggest. A merchant cash advance is a tool. Used for the right need, in the right way, with the cost fully understood, it can be the fastest, most flexible capital a business ever accesses. Used carelessly, it can become exactly the trap owners fear.
In this complete guide, Ashley and Damon Boswell break down what a merchant cash advance actually is, how factor rates and holdback rates work, the three repayment methods providers use, how to calculate the true cost, and the disciplined approach that turns an MCA from a risk into a strategic advantage.
What a Merchant Cash Advance Actually Is
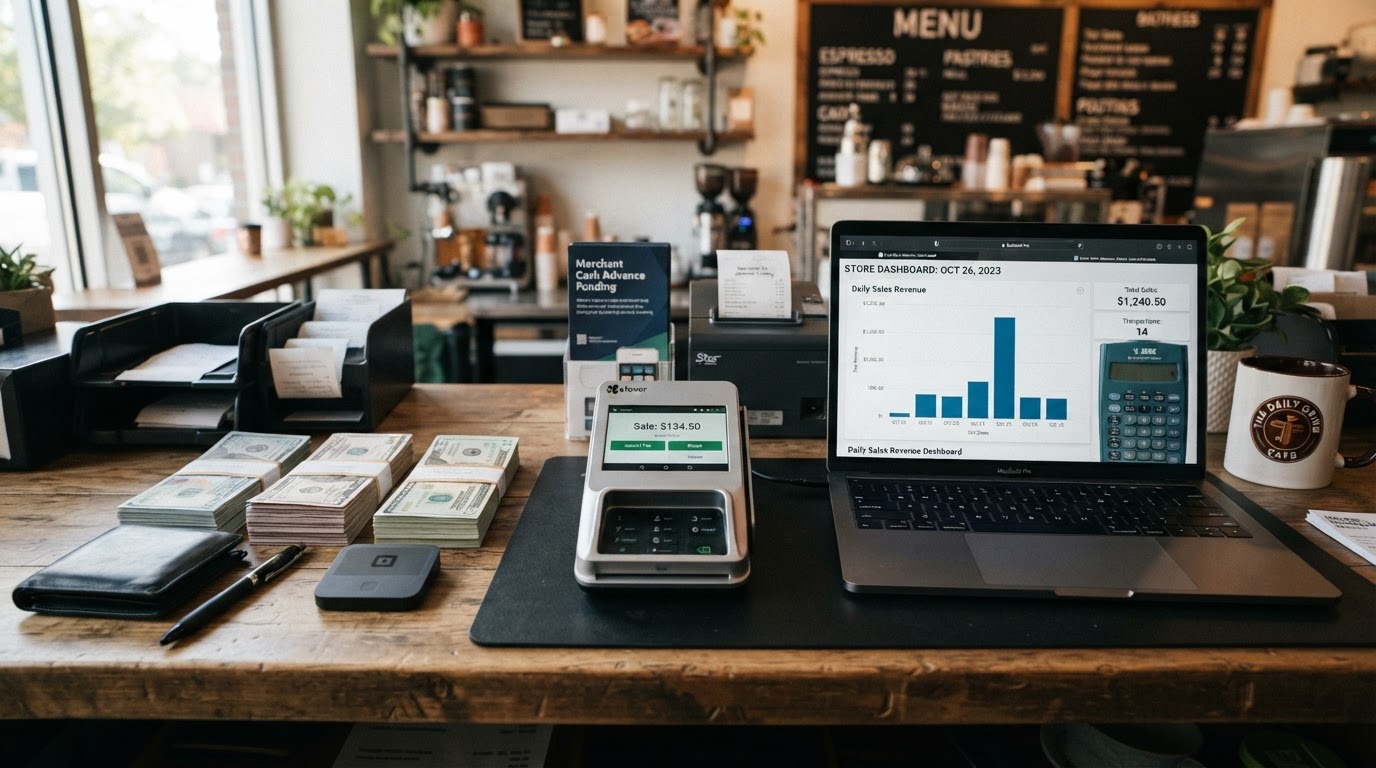
A merchant cash advance is a form of business financing where a provider gives you an upfront lump sum in exchange for a percentage of your future debit and credit card sales, plus a fee. As NerdWallet explains, it is alternative financing — you receive cash today and repay it using a portion of your daily card revenue or fixed withdrawals from your bank account. The defining feature is not the cost; it is the structure. There is no fixed monthly payment and no traditional interest rate. Instead, repayment flexes with your sales.
Ashley Boswell describes it plainly: an MCA is not a loan in the conventional sense. It is the purchase of a portion of your future revenue at a discount. That distinction matters because it shapes how the cost is calculated and how repayment behaves. Damon Boswell adds that this is also why MCAs are accessible to businesses that would not qualify for a traditional bank loan — the provider is underwriting your revenue pattern, not your credit score. According to LendingTree, MCAs are accessible to businesses with limited credit history or inconsistent revenue, with funding that can arrive in as little as a few hours.
Understanding the Factor Rate
The cost of an MCA is expressed as a factor rate, not an interest rate, and this is where most owners get confused. A factor rate is a simple multiplier applied to the amount advanced. As CFG Merchant Solutions explains, factor rates typically range from 1.15 to 1.45. LendingTree and NerdWallet both note the broader market range of 1.10 to 1.50, depending on your industry, time in business, credit, and card revenue.
Ashley and Damon Boswell walk every owner through the math before they ever sign. The formula is straightforward: advance amount multiplied by the factor rate equals the total repayment amount. A $50,000 advance at a 1.30 factor rate means total repayment of $65,000, with $15,000 being the cost of the capital. A $100,000 advance at a 1.20 factor rate means $120,000 total repayment. Damon Boswell stresses that the factor rate is a fixed cost — it does not compound over time like interest, which means paying early does not reduce what you owe. That is a critical difference from a traditional loan, and misunderstanding it is the source of most MCA complaints.
The Holdback Rate: How Repayment Flexes
While the factor rate determines the total amount you repay, the holdback rate determines how fast you repay it. The holdback rate — sometimes called the retrieval rate — is the predetermined percentage of your daily card sales that the provider collects until the advance is fully repaid. NerdWallet notes that holdback rates typically range from 5% to 20%, varying by lender, advance amount, and sales volume.
Damon Boswell explains the mechanics with a concrete example. If your holdback rate is 10% and you generate $5,000 in card sales today, the provider collects $500. If tomorrow you generate $8,000, the provider collects $800. The total amount owed never changes — only the pace of repayment does. On strong sales days you pay more and finish faster; on slower days you pay less and the term extends. Ashley Boswell adds that this flexibility is the genuine advantage of an MCA for businesses with variable revenue. Unlike a fixed monthly loan payment that hits regardless of how the business performed, an MCA's repayment rises and falls with your actual sales.
The Three Repayment Methods
LendingTree identifies three ways MCA providers collect repayment, and Ashley and Damon Boswell make sure every owner understands which method they are agreeing to before signing. The first is split withholding, where the provider partners with your credit card processor to automatically split a percentage of daily card sales between your business and the provider. This is the most seamless method — higher sales mean faster repayment, slower days mean smaller deductions.
The second is lockbox or bank account withholding, where all card sales flow into a separate account first and the provider takes its percentage before transferring the remainder to your business bank account. Damon Boswell cautions that this method involves a one-day delay in receiving your funds, which can put additional pressure on cash flow. The third is direct ACH withholding, where the provider deducts fixed payments from your business checking account based on estimated monthly revenue — closer to a traditional loan structure with a set repayment schedule. Ashley Boswell notes that this third method is better suited for businesses that do not rely heavily on card sales, but it sacrifices the flexibility that makes an MCA valuable in the first place.
Calculating the True Cost: Factor Rate to APR
This is the section Ashley and Damon Boswell spend the most time on, because the factor rate masks the true annualized cost. A factor rate of 1.30 sounds like 30%, but because an MCA is repaid over a short window — often three to twelve months — the effective APR is far higher. LendingTree's own calculations show that a $100,000 advance at a 1.20 factor rate with a $1,000 origination fee and a 120-day repayment term translates to roughly 116% APR. NerdWallet notes that effective APRs on MCAs can range from 40% to 350%, and Nav places the range from 30% to over 350% depending on the factor rate and repayment speed.
Damon Boswell is direct about what this means: the faster you repay an MCA, the higher your effective APR — the exact opposite of a traditional loan where early repayment saves you money. This is the single most important concept to grasp. Ashley Boswell's rule for every owner is to convert the factor rate to an APR before signing, using a calculator, so the cost is comparable to other funding options on the same scale. Never compare a factor rate to an interest rate directly — they are fundamentally different measurements, and treating them as equivalent is how owners get surprised.
How Fast Can You Get Funded?
Speed is the primary reason businesses choose an MCA, and the numbers back it up. Nav reports funding times of one to three days, with advance amounts ranging from $2,500 to over $500,000. NerdWallet notes that many providers can fund the same day you apply, and LendingTree confirms funding can arrive in as little as a few hours for qualified businesses. Credibly, one of the major providers, advertises funding as quickly as four hours with factor rates as low as 1.11.
Ashley Boswell tells owners that this speed is not accidental — it is the core value proposition of the product. The provider is making a decision based on your recent sales data, not a months-long underwriting process. Damon Boswell adds that the businesses that fund fastest are the ones with clean, verifiable bank statements and consistent card revenue. If your deposits are predictable and your processor statements are organized, a provider can make a decision in hours. If your records are messy, even an MCA will slow down.
Qualification: What Providers Actually Review
Qualification for an MCA is more accessible than almost any other funding type, but it is not automatic. NerdWallet notes that new businesses and owners with poor credit may qualify, but you will typically need at least $10,000 in monthly sales. Nav adds that the MCA is based on your business's cash flow and not your business history or credit score — meaning time in business and credit are secondary to the consistency and volume of your deposits.
Damon Boswell's preparation checklist for an MCA is simple: have at least three months of business bank statements ready, ensure your average monthly revenue comfortably exceeds the daily remittance the advance will require, and know your actual card sales volume if you are pursuing a split-withholding structure. Ashley Boswell adds that providers will also look at your existing debt load — if you already have multiple advances or daily-payment obligations stacked, a new provider will see the strain on your account and may decline or reduce the offer. Transparency about existing obligations is essential.
When an MCA Is the Right Tool
Ashley and Damon Boswell recommend an MCA for a specific set of circumstances: when the need is urgent, when the return on the capital is fast and clear, and when the business's revenue can comfortably absorb the daily or weekly remittances. A restaurant needing to replace a broken oven before the weekend rush, a retailer purchasing inventory for a confirmed holiday order, a service business bridging a gap before a large client payment lands — these are textbook MCA use cases where speed and flexibility outweigh the higher cost.
Damon Boswell's test is consistent: if the capital solves a problem worth more than it costs, and the revenue to repay it is already flowing, an MCA is a legitimate tool. If the need is long-term, the return is slow, or the revenue is irregular, a different product — a term loan, a line of credit, or a secured loan — will almost always serve the business better. Ashley Boswell adds that the owners who use MCAs successfully treat them as short-term bridges, not as ongoing operating capital. Rolling one advance into another, month after month, is the pattern that turns a useful tool into a debt cycle.
The Risks: What Every Owner Must Manage
The risks of an MCA are real, and Ashley and Damon Boswell are candid about every one of them. NerdWallet warns that the high cost, coupled with frequent daily or weekly repayments, can easily trap a business in a cycle of debt that is hard to break. Because payments are deducted directly from incoming sales, they reduce the very cash flow the business needs to operate — and if revenue dips, the fixed-percentage remittance can leave too little to cover payroll and rent.
Damon Boswell's cautions are specific. First, never take an MCA without modeling whether your slowest revenue weeks can still absorb the remittance alongside fixed costs. Second, watch for origination fees — LendingTree notes these can run up to $3,000 and significantly increase the overall cost. Third, be wary of providers using confusing contracts, undisclosed fees, or high-pressure tactics; LendingTree explicitly warns to always read the full agreement and confirm the total repayment amount upfront. Ashley Boswell adds the most important rule of all: never stack multiple MCAs. Taking a second advance to cover the remittances of the first is the fastest path to a debt spiral, and it is the pattern that gives the entire product its reputation.
MCA vs. Other Fast Funding Options
An MCA is not the only fast option, and understanding the alternatives helps owners choose correctly. A short-term term loan offers similar speed but with fixed payments that may be more predictable than a percentage-of-sales remittance. A business line of credit provides revolving access where you only pay for what you draw, often at a lower cost than an MCA but requiring stronger credit. Invoice financing is the fastest option of all for B2B businesses with unpaid receivables, sometimes funding within 48 hours, and at a lower effective cost because the invoice itself secures the advance.
Ashley Boswell's guidance is to match the product to the revenue structure. If your revenue is heavily card-based and variable, an MCA's flexible remittance aligns naturally. If your revenue is steady and predictable, a short-term loan's fixed payments may be easier to budget. If your bottleneck is unpaid invoices rather than a general cash gap, invoice financing targets the problem directly and more cheaply. Damon Boswell notes that for owners who qualify for a line of credit, that revolving structure is almost always preferable to an MCA — the MCA's role is to serve businesses that cannot yet access that line.
Is a Merchant Cash Advance Right for You?
Damon Boswell's readiness test for an MCA is direct: Is your need urgent enough that a faster, lower-cost option like a line of credit is not available or not fast enough? Is the use of funds tied to a clear, near-term return — inventory for a confirmed order, equipment that restores revenue, a bridge to a known payment? Can your slowest revenue weeks absorb the daily remittance alongside all fixed costs? Have you converted the factor rate to an APR so you understand the true cost? And are you certain you will not need to stack a second advance to repay this one? If you can answer yes to all five, an MCA is a legitimate, strategic tool. If any answer is no, a different path will serve you better.
If you are unsure where your business stands, that is exactly what our AI Funding Match Calculator is built to clarify. The calculator weighs your revenue, credit, timeline, and goals, and Ashley and Damon Boswell review every result personally. On a short phone call — no Zoom required — we will help you determine whether an MCA or another fast-funding path is the right fit for your situation and your numbers.
The Bottom Line
A merchant cash advance is neither a trap nor a bargain — it is a fast, flexible, higher-cost tool built for urgent, short-term needs backed by reliable revenue. The owners who use it well understand the factor rate, convert it to a true APR, model whether their slowest weeks can absorb the remittance, and treat the advance as a bridge rather than a permanent facility. The owners who get hurt by it skip the math, stack advances, and use the capital for returns that arrive too slowly to repay it. Ashley and Damon Boswell have helped owners across the United States, Puerto Rico, and Canada use MCAs strategically, and the businesses that succeed are the ones that enter the product with their eyes open.
See whether an MCA fits your business. Complete the AI Funding Match Calculator in under 60 seconds, and Ashley and Damon Boswell will walk through your matches, your true cost, and your next step on a quick phone call — so if speed is what you need, you get it without the trap.
Ashley Boswell and Damon Boswell
Funding specialists at ASAP Capital Solutions, helping business owners find the right capital across the United States, Puerto Rico, and Canada.
Find Your Funding Match in 60 Seconds
Complete the AI Funding Match Calculator and Ashley and Damon Boswell will review your matches on a quick phone call.
Get My Funding Match