For business owners with strong personal credit, one of the most overlooked sources of capital is sitting right in their wallet: 0% APR business credit cards. Used strategically, a technique called credit card stacking can turn several interest-free card offers into a meaningful pool of working capital — sometimes $50,000 to $100,000 or more — with no interest for 6 to 18 months. At ASAP Capital Solutions, Ashley and Damon Boswell help owners understand when this strategy fits and, just as importantly, when it does not.
In this guide, Ashley and Damon Boswell break down what 0% credit card stacking is, how it works, who it benefits, and the risks every owner needs to manage before pursuing it.
What Is 0% Credit Card Stacking?
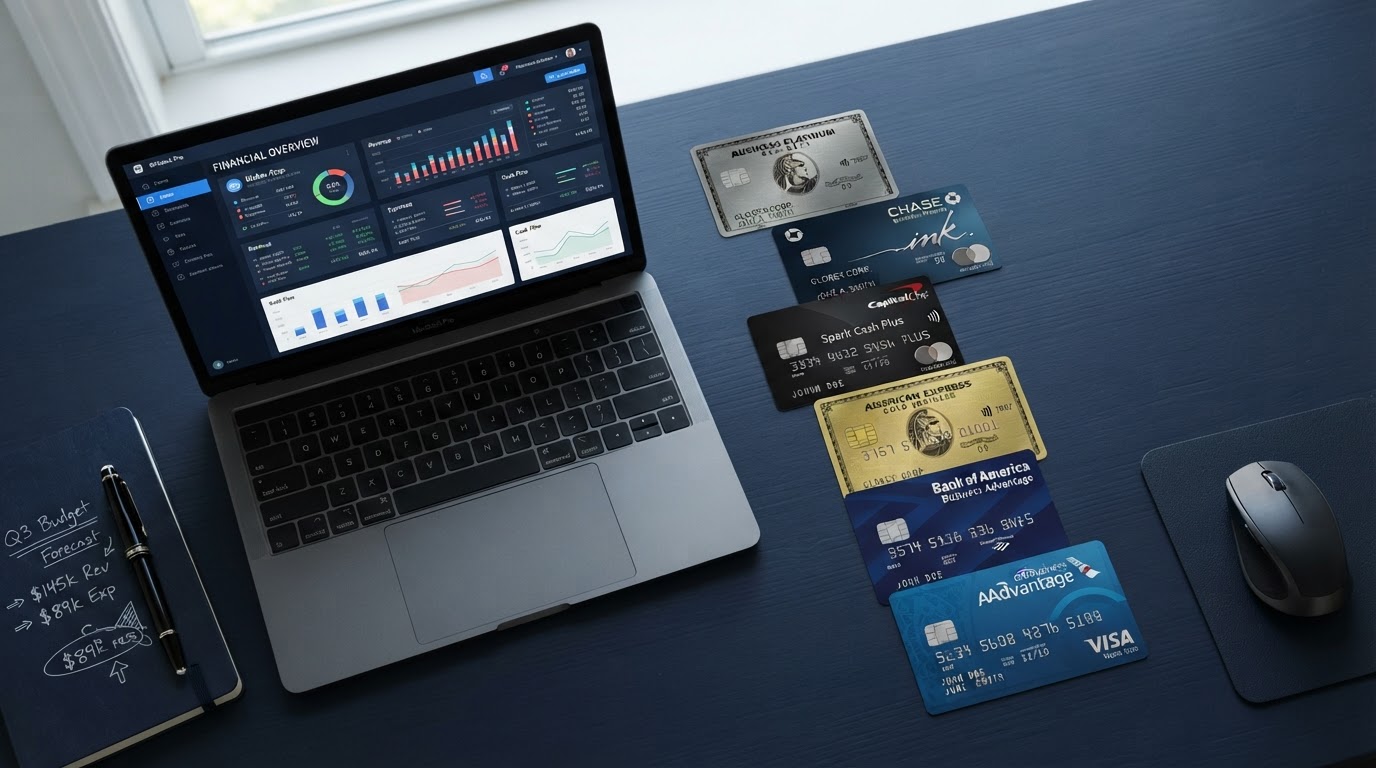
Credit card stacking is an alternative financing method where a business owner applies for multiple credit cards within a short timeframe to create a larger combined pool of credit. As Brex explains, instead of getting one business loan, the owner gets several credit cards — assembling a makeshift credit line by piecing together what multiple card issuers are willing to give. If one card approves you for $15,000 and another for $20,000, you have effectively created $35,000 in available business credit.
Ashley Boswell describes it as building your own unsecured line of credit, card by card. The strategy is completely legal — it is simply an unconventional approach owners use when traditional loan options are limited or unavailable. The goal is to maximize available credit while minimizing initial cost, and the most powerful version targets cards with 0% introductory APR offers.
How the 0% APR Window Works
The appeal of stacking lies in the interest-free promotional period. Most 0% APR business credit cards offer interest-free financing on purchases for 6 to 18 months. By applying for several cards at once, an owner can juggle multiple parallel interest-free windows, effectively extending the runway before any interest becomes a factor. Fund&Grow notes that with a phased stacking strategy, access to 0% offers can be extended over longer periods than what a single card provides — sometimes beyond 24 months.
Damon Boswell emphasizes the math: if each of five cards offers a $20,000 limit at 0% for 12 months, the business has roughly $100,000 in accessible, interest-free capital to deploy toward inventory, marketing, equipment, or growth initiatives — as long as the balances are managed and paid down before the promotional periods expire.
Who Should Consider Credit Card Stacking?
This strategy is not for every business. Brex points out that most business credit cards require a personal guarantee and good personal credit, typically a score in the 680 to 700 range or higher to successfully open multiple cards at once. AMP Advance adds that stacking works with zero revenue, making it a fit for early-stage startups and pre-revenue businesses that have strong personal credit but no collateral for traditional loans.
Ashley and Damon Boswell recommend stacking for owners who fit a specific profile: strong personal credit, a clear path to revenue that will allow balances to be paid off within the promotional window, and the discipline to manage multiple payment schedules without missing dates. It is especially powerful for startups and newer businesses that need capital to reach profitability but cannot yet qualify for revenue-based funding.
The Benefits: No Collateral, Interest-Free Capital
The advantages are significant. Business credit cards are unsecured, so no business assets or personal property need to be pledged — a major advantage for owners who lack collateral for traditional loans. The 0% APR periods provide genuine interest-free capital for months, and stacking can deliver more total funding than any single card would offer. When kept in good standing, business credit card accounts typically do not report to personal credit, protecting the owner's personal credit profile.
Damon Boswell also highlights the flexibility: unlike a lump-sum loan, stacked credit can be drawn as needed, repaid, and reused during the promotional window. For a business bridging a gap before a busy season or awaiting client payments, that on-demand structure is invaluable.
The Risks: What Every Owner Must Manage
The benefits come with serious responsibilities. Those attractive 0% APR offers eventually expire — typically after 12 to 18 months — at which point interest rates jump significantly. Brex warns that missing a payment or failing to manage multiple cards properly can trigger expensive interest charges that quickly spiral into unmanageable debt. Because most cards require a personal guarantee, the owner is personally responsible if the business cannot pay.
Ashley Boswell stresses three rules to every owner considering stacking: never stack without a concrete plan to pay down balances before the promotional period ends, never use the capital for expenses that produce no return, and never miss a payment — a single missed payment can end the 0% offer early and damage the personal credit that makes the whole strategy possible.
Stacking vs. Other Funding Options
0% credit card stacking is one tool among many. For owners with weaker credit or no personal guarantee to offer, revenue-based options like a business cash advance may be more realistic. For larger, longer-term investments, a secured loan leveraging assets can deliver more capital at a lower overall cost. A business line of credit offers similar flexibility to stacking but through a single facility. Each tool has a job it does best, and Ashley and Damon Boswell help owners weigh them against one another rather than defaulting to whichever option is easiest to pitch.
The mistake Damon Boswell sees most often is owners treating stacking as a long-term solution. Credit cards work best for short-term capital needs that can be paid off within the interest-free window. Stretching balances beyond that window turns a smart, low-cost strategy into an expensive one.
Is 0% Credit Card Stacking Right for You?
If you have strong personal credit — generally in the higher ranges — limited collateral, and a clear, time-bound use for the capital, 0% credit card stacking can be one of the lowest-cost funding paths available. If your credit is fair or challenged, or your need is long-term, other options will serve you better. The right answer depends on your credit profile, your timeline, and the specific use of funds.
That is exactly what our AI Funding Match Calculator is built to determine. The calculator weighs your answers and surfaces the funding paths most likely to fit your profile. Ashley and Damon Boswell then review every result personally, and on a short phone call — no Zoom required — we will help you confirm whether 0% credit card stacking or another path is the right move for your business.
The Bottom Line
0% credit card stacking is a powerful, legitimate strategy for accessing interest-free business capital — but it rewards discipline and punishes carelessness. Done right, it can give a credit-strong business tens of thousands of dollars in free working capital for a year or more. Done wrong, it can create expensive debt that damages both the business and the owner's personal credit. Ashley and Damon Boswell have helped owners across the United States, Puerto Rico, and Canada use this strategy responsibly, and the businesses that succeed are the ones that enter it with a plan.
Curious whether stacking fits your profile? Complete the AI Funding Match Calculator in under 60 seconds, and Ashley and Damon Boswell will review your matches on a quick phone call to help you choose the path that fits your credit, revenue, and goals.
Ashley Boswell and Damon Boswell
Funding specialists at ASAP Capital Solutions, helping business owners find the right capital across the United States, Puerto Rico, and Canada.
Find Your Funding Match in 60 Seconds
Complete the AI Funding Match Calculator and Ashley and Damon Boswell will review your matches on a quick phone call.
Get My Funding Match