Most business owners who get denied funding are not denied because their business is broken. They are denied because they walked into the process unprepared. At ASAP Capital Solutions, Ashley and Damon Boswell see it constantly: an owner with solid revenue and a real need loses out on capital simply because their bank statements tell a messy story, their documents are incomplete, or they never understood what the underwriter was actually looking for.
The good news is that preparation is entirely within your control. In this guide, Ashley and Damon Boswell walk through exactly what lenders and funding partners review, the documents you should have ready before you ever apply, and the financial habits that turn your business into an obvious yes. Whether you are pursuing a small business loan, a business cash advance, a line of credit, or a secured loan, the fundamentals of readiness are the same.
What Underwriters Actually Look At
Underwriting is the process a lender uses to assess whether your business can repay the funding. As Ramp explains in its guide to business loan underwriting, underwriters closely examine financial statements — including profit and loss statements, balance sheets, and cash flow reports — and they look for a debt-service coverage ratio (DSCR) of 1.25 or higher, which generally indicates your business earns enough to comfortably cover its loan payments.
Ashley Boswell translates that into plain terms for every owner she speaks with: the underwriter is asking one question — can this business afford to pay this back? They answer it by looking at your revenue consistency, your existing debt load, your cash reserves, and the strength of your deposits. Damon Boswell adds that different funding types weight those factors differently. A business cash advance leans heavily on your deposit history and revenue pattern. A traditional small business loan weighs credit and financial statements more heavily. A secured loan adds the value of your collateral into the equation. But every one of them starts from the same foundation: clean, verifiable, consistent financials.
The Documents You Should Have Ready
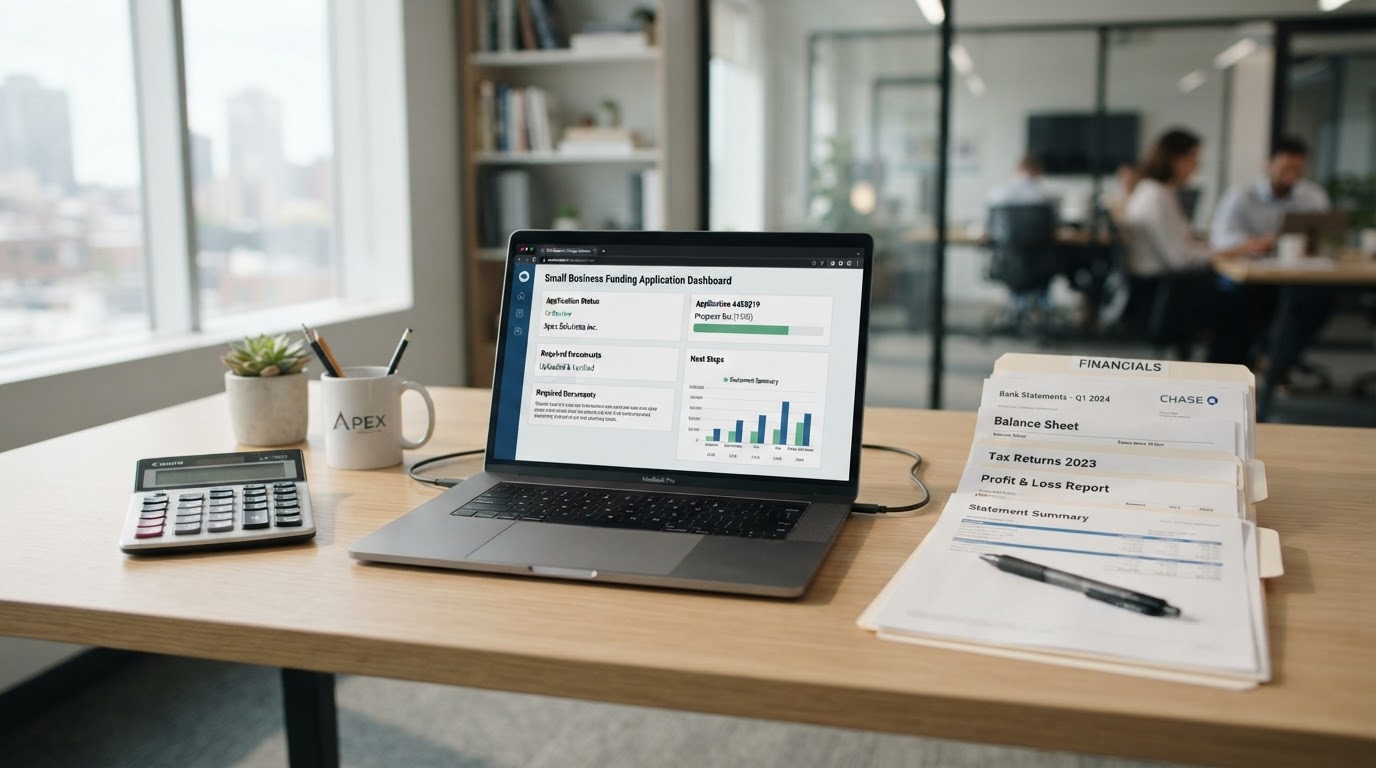
Before you apply for anything, gather your documents. The U.S. Chamber of Commerce notes that lenders typically require tax returns, bank statements, profit and loss statements, and a clear explanation of how the capital will be used. Credibly adds that alternative lenders often simplify the process, sometimes requiring only a financial application and three to four months of bank statements to get started — but having more ready never hurts.
Damon Boswell's standard document checklist for every owner is straightforward: three to six months of recent business bank statements, a current profit and loss statement if you have one, business and personal identification, a debt schedule listing what you already owe, and a short, specific explanation of how the funds will be used. Ashley Boswell stresses that last point — a clear use of funds builds lender confidence and speeds approval. Saying 'growth' is vague; saying 'purchase $40,000 in inventory for the holiday season, which historically triples our monthly revenue' is compelling.
Your Bank Statements Tell Your Story
Of all the documents you will submit, your bank statements carry the most weight for most funding types. As the U.S. Chamber of Commerce explains, bank statements give lenders a glimpse into your deposits, withdrawals, and balances — revealing your financial health, your ability to repay, and whether you carry outstanding debt. They also reveal whether your income is consistent and reliable or irregular and unpredictable.
Ashley and Damon Boswell tell every owner to read their own bank statements before a lender does. Look for three things: consistent daily or weekly deposits that prove steady revenue, a healthy average daily balance that shows you are not running the account to zero, and an absence of red flags like nonsufficient funds (NSF) charges, overdrafts, or large unexplained withdrawals. Damon Boswell notes that a few NSFs will not automatically disqualify you, but a pattern of them signals cash-flow instability that makes any underwriter nervous.
Understand the Cost Before You Sign
Preparation is not only about documents — it is about understanding what you are agreeing to. Different funding products price themselves differently, and confusing one for another is a costly mistake. A business cash advance uses a factor rate rather than an interest rate. As eCapital explains, a factor rate is a fixed multiplier applied to the advance amount — for example, a $50,000 advance at a 1.3 factor rate means total repayment of $65,000, with $15,000 being the cost of the advance.
The critical nuance, as LendingTree highlights, is that factor rates are not annualized like traditional interest rates. A factor rate of 1.35 sounds like 35%, but when converted to an APR over a short repayment window, the effective cost can be far higher. Luca AI's 2026 guide puts a fine point on it: the faster you repay an MCA, the higher your effective APR — the exact opposite of a traditional loan where early repayment saves you money. Ashley Boswell's rule is simple: never sign for any funding until you understand the total dollar cost, the repayment schedule, and how that cost compares to the return the capital will generate. If the math does not work, the funding is not right, no matter how fast it arrives.
The Habits That Make You an Obvious Yes
Beyond documents, the day-to-day habits of your business shape your approval odds. Ramp recommends organizing your financial documents, checking and improving both personal and business credit, maintaining strong cash flow, and being transparent and responsive when a lender requests information. The Accion Opportunity Fund reinforces that the last three to six months of bank statements are usually required, and that all documents should be complete, signed, and up to date.
Damon Boswell distills it into four habits every owner should build long before they need funding. First, keep your business deposits clean — run revenue through your business account, not a personal one, so the paper trail is obvious. Second, maintain a buffer in your operating account so a single slow week does not trigger overdrafts. Third, monitor your credit and resolve errors or collections proactively rather than discovering them during an application. Fourth, keep your financial statements current — a P&L from eighteen months ago signals a business that is not tracking its own numbers. Ashley Boswell adds a fifth: be responsive. When a lender asks a question, a fast, complete answer often matters as much as the answer itself.
Match the Funding to the Need
Being prepared also means knowing which funding type fits your situation, because applying for the wrong product wastes time and can ding your credit. A business cash advance is built for speed and flexibility when revenue can support repayment. A small business loan offers lower overall cost for larger, planned investments but demands stronger credit and financials. A business line of credit provides reusable, on-demand capital for ongoing needs. Invoice financing targets the specific problem of slow-paying customers. A secured loan leverages owned assets for larger amounts at lower rates. And 0% credit card stacking delivers interest-free capital for credit-strong owners with a disciplined repayment plan.
Ashley and Damon Boswell never recommend applying blindly. The right path depends on your revenue, credit, timeline, and the specific use of funds — and applying for the wrong one first can leave a hard inquiry on your credit without producing capital. That is why matching the funding to the need is the final, and arguably most important, step in preparation.
How to Know When You Are Ready
Damon Boswell's readiness test is practical: Can you produce three to six months of clean bank statements on demand? Is your average daily balance healthy with no pattern of overdrafts? Do you know your personal and business credit standing? Can you state a specific, revenue-justified use for the capital? And do you understand the total cost and repayment structure of the funding type you are pursuing? If you can answer yes to all five, you are prepared. If any answer is no, that is the gap to close before you apply.
If you are unsure where you stand, that is exactly what our AI Funding Match Calculator is built to clarify. The calculator weighs your revenue, credit, timeline, and goals, and Ashley and Damon Boswell review every result personally. On a short phone call — no Zoom required — we will help you identify which funding path fits, what documents you will need, and whether your business is ready to apply today or has a gap to close first.
The Bottom Line
Funding approval is rarely about luck. It is about preparation — clean bank statements, organized documents, an understood cost structure, and the right funding type matched to the right need. Ashley and Damon Boswell have helped owners across the United States, Puerto Rico, and Canada get ready before they apply, and the businesses that succeed are the ones that treat preparation as an ongoing habit rather than a last-minute scramble.
See where your business stands. Complete the AI Funding Match Calculator in under 60 seconds, and Ashley and Damon Boswell will walk through your readiness, your matches, and your next step on a quick phone call — so when the time comes to apply, you are already an obvious yes.
Ashley Boswell and Damon Boswell
Funding specialists at ASAP Capital Solutions, helping business owners find the right capital across the United States, Puerto Rico, and Canada.
Find Your Funding Match in 60 Seconds
Complete the AI Funding Match Calculator and Ashley and Damon Boswell will review your matches on a quick phone call.
Get My Funding Match